LIVE TAX STRATEGY WORKSHOP
Discover how a $50K down payment could offset $400K in active income taxes
Designed for high-income business owners who want a serious tax strategy in place before the next major tax deadline hits…
If that is you, click the button below to join our live workshop this Sunday!
We’ll review the strategy, see if you qualify, and walk you through the next step.
STRATEGIC COMPARISON
Stop Waiting Until Tax Season
to Start Planning
Traditional tax preparation looks backward at capital you have already lost. True wealth protection requires evaluating asset acquisitions and legal deductions well before the fiscal year concludes.
THE CONVENTIONAL TRAP
WITHOUT....
Standard compliance merely aggregates completed financial history. Once capital has been deployed and the year closes, legal mitigation tools evaporate.
Waiting until tax season and hoping your CPA finds something
Playing defense while your tax bill keeps getting bigger
Relying only on basic tax prep when you may need advanced planning
Result: 100% Capital Outflow with Zero Long-Term Wealth Created
THE ARCHITECTURAL SHIFT
SO YOU CAN......
✓ Explore a leverage depreciation strategy
✓ Potentially create a major first-year deduction
✓ Use business-use assets to reduce taxable income legally
✓ Get clarity before your next quarterly payment or tax deadline
Note: You must be:
✓ A business owner or professional with a meaningful tax liability
✓ Open to advanced depreciation-based tax planning
✓ Ready to take action if the strategy is a fit
SCROLL TO LEARN MORE ↓
LEVERAGE MULTIPLIER ARCHITECTURE
See How the Strategy Could Work
A rigorous, statutory breakdown demonstrating how prudent liquidity deployment unlocks full-basis accelerated depreciation under current IRC provisions.
Prudent liquidity deployment allocating 12.5% equity to initiate asset acquisition structure.
Acquisition of commercial fleet asset or heavy business equipment financed via non-recourse or asset debt.
Qualifying Section 179 and statutory bonus depreciation rules applied directly against entire acquisition basis.
Deductions significantly offset high-bracket active income, converting tax liabilities into balance sheet equity.
A Simple Look at the Strategy Mechanics
Follow this illustrative four-stage structure from initial capital deployment through the potential depreciation benefit.
Prudent liquidity deployment allocating 12.5% equity to initiate the asset acquisition structure.
Acquisition of a commercial fleet asset or heavy business equipment financed through an asset-based structure.
Qualifying Section 179 and applicable bonus depreciation rules may be applied against the acquisition basis.
The illustrative structure demonstrates how deductions may offset qualifying income while capital is deployed into a business asset.
Business Equipment & Vehicle Mechanics
Under applicable Internal Revenue Code provisions, certain equipment and qualifying business vehicles placed into active commercial service may qualify for accelerated depreciation treatment.
Statutory Disclaimer: Numerical figures depict illustrative statutory frameworks under IRC §§ 168(k) & 179. Actual deductions vary by taxpayer active participation status, material participation, business use percentages, and current tax year thresholds. Consult certified tax counsel for personalized execution.
WORKSHOP FACULTY & LEADERSHIP
Experienced Perspectives
Across Investment & Strategy
Three proven practitioners bridging high-yield fund mechanics, aggressive tax mitigation, and institutional business advisory.
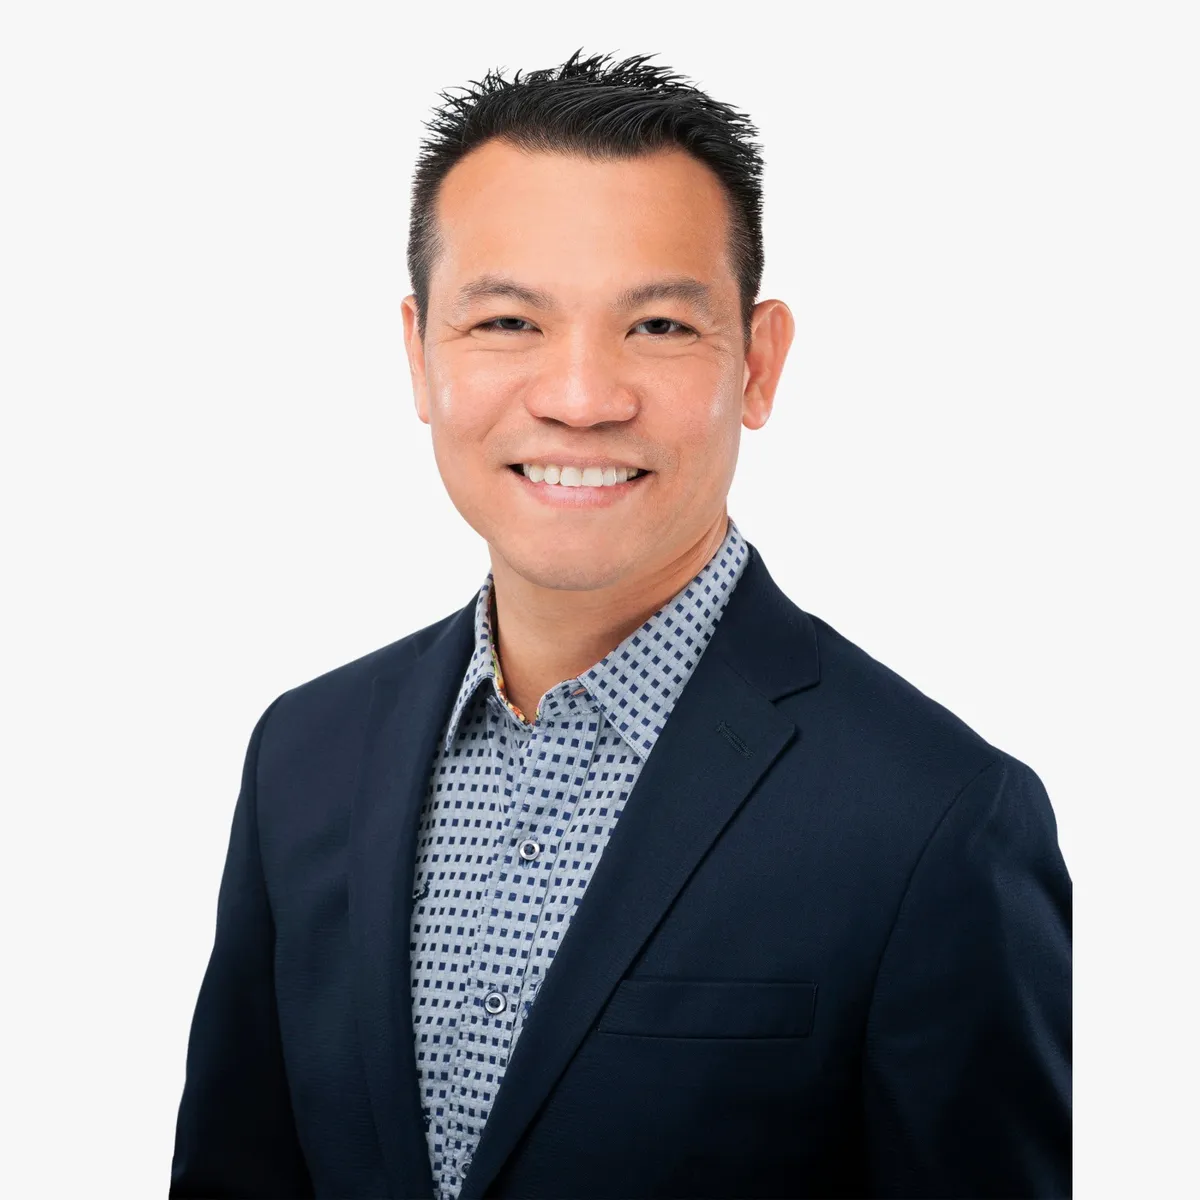
Tim Mai
FUND MANAGER & REAL ESTATE STRATEGIST
Fund Structuring Syndication Asset Protection
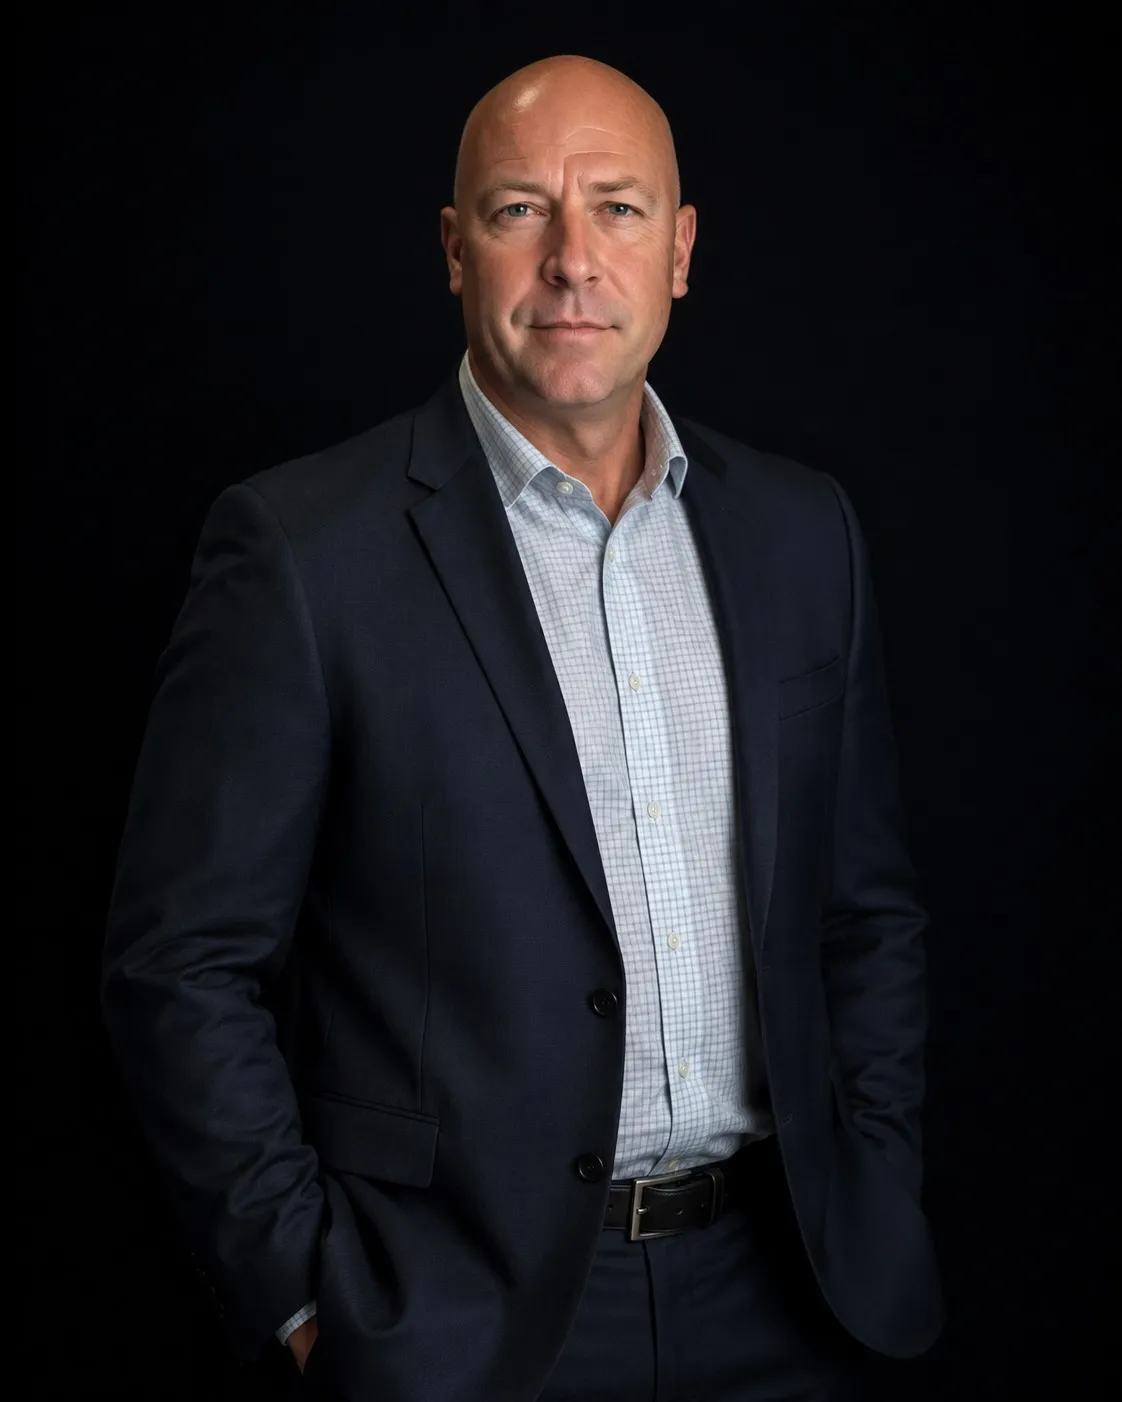
Chris Craig
TAX STRATEGY EXPERT & CPA ADVISOR
Tax Mitigation Depreciation IRS Compliance
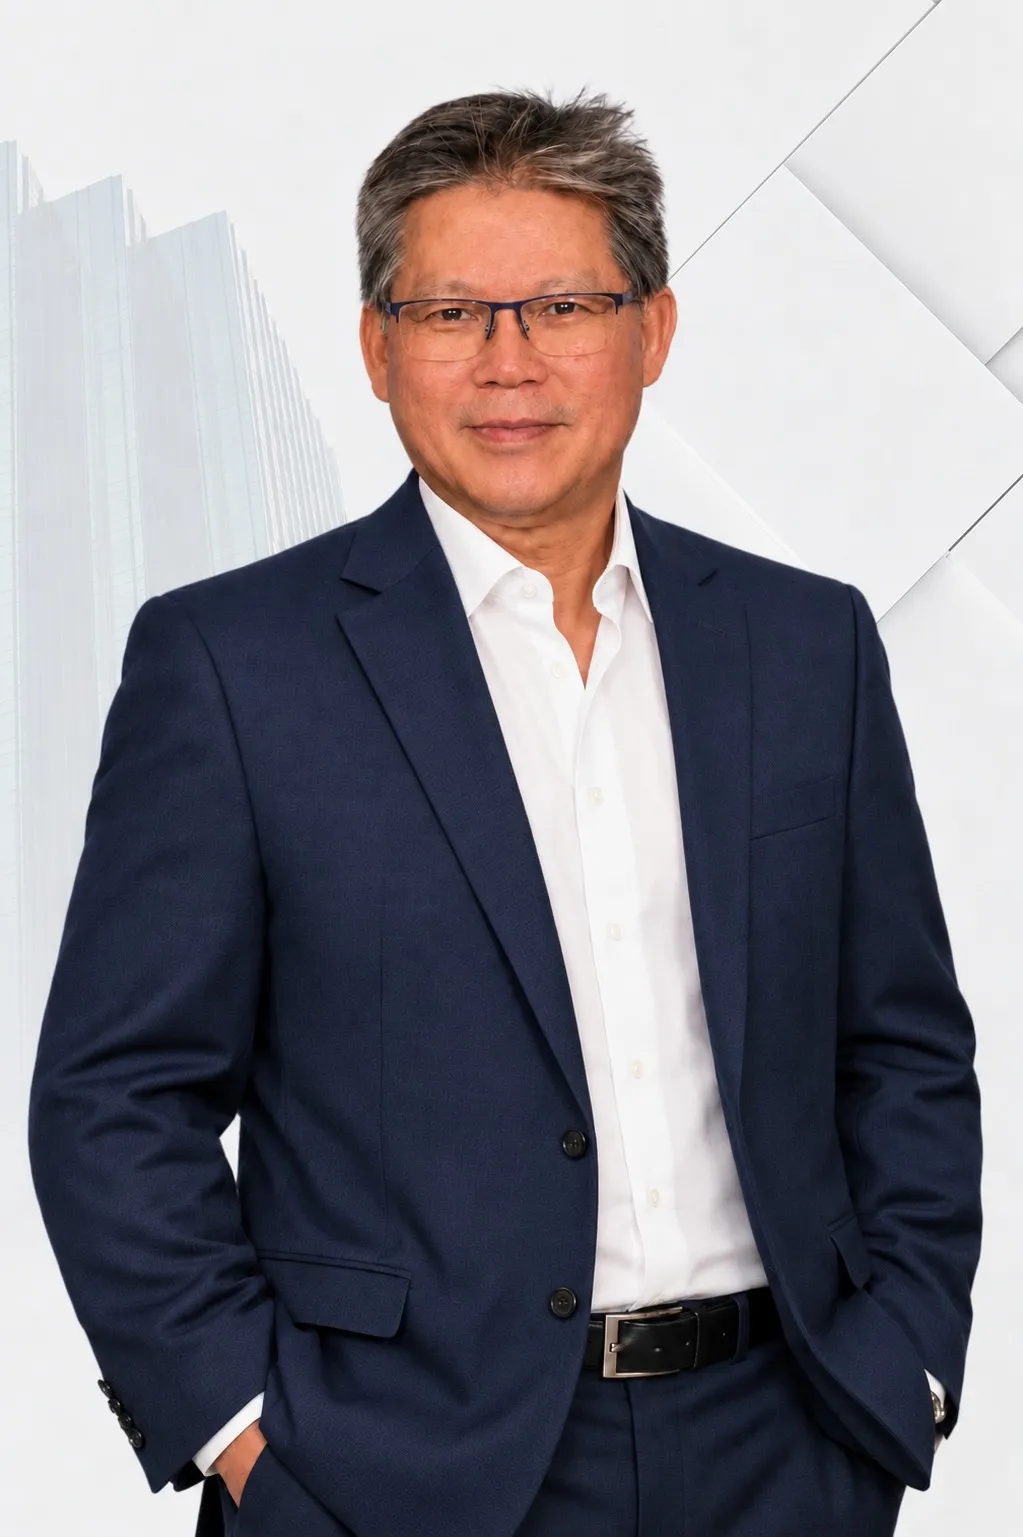
Sadikin Budiman
BUSINESS ADVISOR & WEALTH ARCHITECT
M&A Advisory Enterprise Scaling Succession
COMPLETE YOUR REGISTRATION
Reserve Your Seat
- Live Strategy Workshop: Walk through live mathematical models of active asset acquisitions
- Advanced Depreciation Education: Master cost segregation protocols, Section 181, and bonus write-offs
- Asset Strategy Breakdown: Architectural debt-to-equity frameworks to protect cash reserves
- Direct Strategic Q&A: Private access to executive strategists to review asset qualification
✓Live Strategy Workshop: Walk through live mathematical models of active asset acquisitions | ✓Advanced Depreciation Education | ✓Direct Strategic Q&A: Private access to executive strategists to review asset qualification
Have a specific institutional compliance or family office structuring inquiry? Contact [email protected] for private coordinator dispatch.
MANDATORY INSTITUTIONAL & REGULATORY DISCLOSURES
Educational and Informational Context Only: The Executive Tax Strategy Workshop, associated curriculum, analytical models, and financial schematics presented by Sadikin & Friends are compiled strictly for executive educational and strategic orientation purposes. Participation in this briefing, receipt of program collateral, or interactive inquiry does not establish an attorney-client, certified public accountant-client, registered investment advisory, or formal fiduciary relationship between the attendee and Sadikin & Friends or its presenting specialists.
No Professional Tax, Accounting, or Legal Counsel: The mechanics discussed, including capital allocation models, accelerated depreciation frameworks, and multi-entity architectures, reflect generalized interpretations of the Internal Revenue Code and relevant regulatory precedent. Tax codes remain subject to municipal, state, federal, and judicial reassessment. Nothing contained herein constitutes bespoke tax, legal, or accounting advice. Participants must consult independent licensed tax attorneys and certified public accountants prior to executing any structuring or altering current filing positions.
Individual Variance in Outcomes & Circular 230 Disclosure: Hypothetical scenarios, financial multipliers, and historical tax deductions are illustrative; outcomes vary significantly based on individual income thresholds, entity classification, material participation status, and jurisdiction. Pursuant to Treasury Department Circular 230 regulations, any federal tax information included in this presentation or associated documentation was not intended or drafted to be utilized, and cannot be utilized by any taxpayer, to evade penalties imposed under federal tax law.


© 2026 Sadikin & Friends Wealth Advisory. All rights reserved. Executive Tax Strategy Workshop is an institutional education initiative.